A collision caused by an uninsured driver can leave you with medical bills, lost income, vehicle damage, and no at-fault driver's insurance company to turn to. Missouri law requires automobile liability insurance, but not every driver on St. Louis roads carries it. If the driver who hit you has none, the coverage that answers is usually your own.
At Sumner Law Group, LLC, we help injured people pursue uninsured motorist (UM) claims when another driver's lack of insurance creates another obstacle after a crash. Our boutique trial practice has more than 50 years of combined legal experience, and our attorneys prepare cases with the expectation that an insurer may have to answer difficult questions in court.
If an uninsured driver caused your injuries, call (314) 669-0048 for a free case review. There are no upfront fees, and you don't pay us anything unless we recover money for you.
Why Work With Our St. Louis Uninsured Motorist Lawyers After a Crash
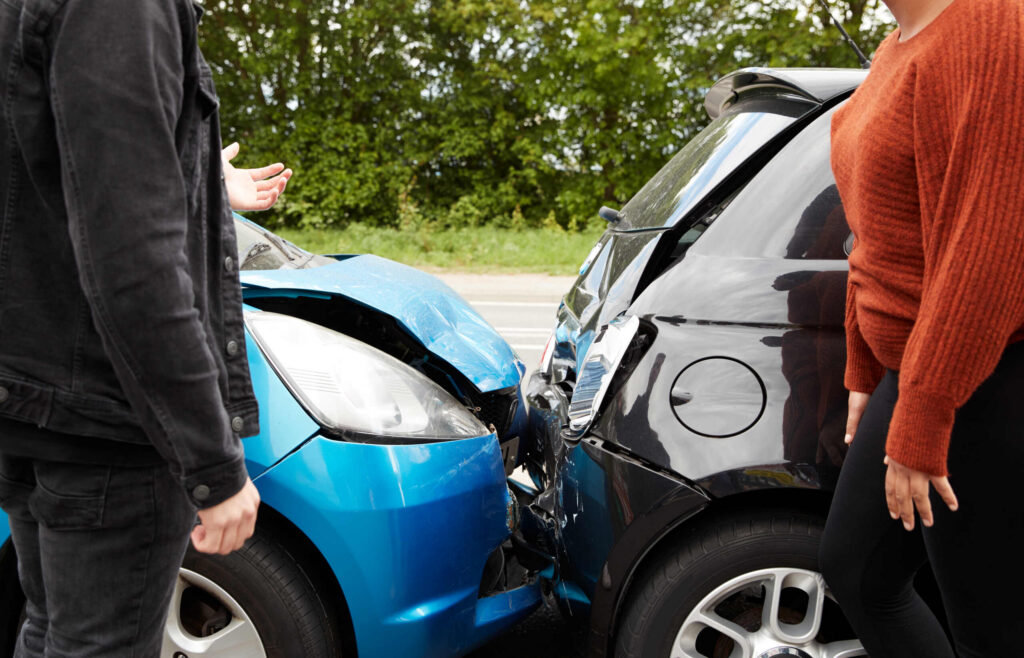
An uninsured motorist claim is filed under your own policy, which does not make it simple. Your insurer owes you UM benefits and also decides how much to pay, which can produce a dispute over liability, causation, damages, or the amount of available coverage.
We approach these cases as litigation matters from the beginning. That means looking beyond the police report and asking questions such as:
- How did the collision happen?
- Was the other driver actually uninsured?
- What does your automobile policy provide?
- Was there more than one applicable policy?
- What evidence establishes the other driver's fault?
- Did the collision cause the injuries being claimed?
- What losses are likely to continue into the future?
The answers determine how the claim is presented and what evidence it needs.
A UM claim is unusual in one respect: the company evaluating it is the one you pay premiums to, and the claim is still adversarial in structure. Clients work directly with the attorneys handling their case, and we prepare the file for court from the first week rather than after an offer arrives.
What Are Your Options After a Crash With an Uninsured Driver?
When the at-fault driver has no insurance, your first step is identifying every potential source of coverage. Your own UM coverage may provide a path to compensation for covered bodily injuries. Depending on the circumstances, other insurance coverage may also need to be investigated.
Under Section 379.203, no automobile liability policy may be issued for delivery in Missouri unless uninsured motorist coverage is provided, at limits not less than those set by Section 303.030. You very likely carry it whether or not you remember selecting it.
Your declarations page, which is the summary page showing your coverages and limits, may show the UM amount. The policy itself can contain additional provisions that affect how a claim is evaluated. We review the policy alongside the facts of the collision instead of assuming that the declarations page tells the entire story.
The other driver having no insurance does not end the coverage investigation. Questions may arise about whether the vehicle was owned by someone else, whether another policy applies, or whether another person or entity may bear legal responsibility for the crash.
Section 379.203 also treats a vehicle as uninsured when the at-fault driver's liability insurer is insolvent and cannot pay within the required limits. A policy that existed on paper is not always coverage that answers.
Health insurance may help pay medical bills while an injury claim is being evaluated, but it is not a substitute for a personal injury recovery. Lost income, future care, physical impairment, and other losses can also matter when determining damages.
Don't jeopardize your settlement: discover the specific statements to avoid when speaking with insurance companies following an accident.
Before deciding which option to pursue, have the available insurance and potential sources of recovery reviewed. Contact our firm at (314) 669-0048 to schedule a free case review.
Call Us Now! Your Time to
File a Claim Is Limited.
How Do You File a St. Louis Uninsured Motorist Claim?
Filing a UM claim starts with establishing the collision, the other driver's responsibility, the absence of applicable liability insurance, and the injuries caused by the crash. The process can involve several stages. These include the following:
Report the Collision
A police report can provide an important record of the crash. The report may identify the drivers, vehicles, apparent circumstances of the collision, witnesses, citations, and insurance information available at the scene. The report is evidence, but it is not necessarily the final word on liability.
Obtain the Insurance Information
You should obtain the other driver's insurance information if possible, and if the driver has none, documentation supporting that fact becomes important to the UM claim. Your own policy also needs to be reviewed. Do not treat your insurer's first description of your coverage as the complete legal analysis.
Document Your Injuries
Records tie the collision to the losses being claimed. Keep records of medical appointments, billing statements, rehabilitation, diagnostic testing, and expenses. If an injury affects your work, documentation of lost wages and changes in your ability to earn income can also become important.
Notify Your Insurer
Your policy may contain provisions concerning notice of an accident and a UM claim. The timing and method of notice can matter, so review your policy and communicate carefully with the insurer.
This is because a UM claim is not simply a request for your insurer to write a check. It is a claim governed by the insurance contract and Missouri law.
Investigate Before Discussing Settlement
An insurer may request a recorded statement, medical authorization, documentation, or other information while evaluating your claim.
You should understand why the information is being requested and how it relates to the claim before providing it. Statements about your injuries, prior medical history, or the circumstances of the accident can become part of the insurer's evaluation. Our lawyers can handle communications and investigate the evidence while developing the claim.
Missouri's Protections for People Injured by Uninsured Drivers
Missouri requires motorists to maintain financial responsibility, and the state's uninsured motorist statute provides an additional layer of protection for people injured by uninsured motorists.
Missouri's minimum automobile liability requirements are $25,000 per injured person for bodily injury, $50,000 per accident, and $25,000 for property damage. But minimum liability insurance and UM coverage are separate issues.
A driver can violate Missouri's insurance requirements and still cause an accident. Your UM coverage exists to address circumstances in which an at-fault motorist lacks the liability coverage that would otherwise be available.
UM coverage is primarily associated with bodily injury caused by an uninsured motorist. Whether particular losses are covered depends on the policy language and the accident facts.
Property damage is a separate question. UM bodily injury coverage should not automatically be treated as coverage for damage to your vehicle.
Uninsured Is Not the Same as Underinsured
These two coverages are confused constantly, including on legal websites, and the distinction decides which claim you have. Uninsured motorist coverage answers when the at-fault driver carried no liability insurance at all. Underinsured motorist coverage answers when they carried some, but not enough to cover the harm.
The practical difference in Missouri is that one is required and the other is not. Section 379.203 mandates UM coverage on every automobile liability policy issued for delivery in the state. No parallel provision requires underinsured coverage, so whether you carry it turns on what your policy says. Check the declarations page for both before assuming which claim applies.
What Happens to the Claim Against the Uninsured Driver
When your insurer pays a UM claim, Section 379.203 gives it a right to the proceeds of any settlement or judgment you later obtain from the party responsible for your injuries. That is why the claim against the at-fault driver does not simply disappear once your own coverage responds, and why the two need to be handled together rather than in sequence.
What If the Driver Fled the Scene?
Section 379.203 addresses this directly. UM coverage reaches a crash where the identity of the owner or operator cannot be established because they left the scene, and it applies whether or not physical contact was made between the vehicles.
That second point matters more than most people realize. A driver forced off the road by a vehicle that never touched them, and that did not stop, is describing exactly the situation the statute contemplates. Evidence can be particularly important in these cases. License plate information, surveillance video, dashcam footage, witness statements, photographs, and the police investigation may help identify the vehicle or establish what happened.
If you were injured in a St. Louis hit-and-run, we can review the available evidence and insurance coverage to determine what options may exist.
What Compensation Can an Uninsured Motorist Claim Provide?
The potential value of a UM claim depends on the policy, the available limits, liability, and the injuries and losses supported by the evidence. Depending on the circumstances, a UM claim may address losses such as:
- The documented cost of care connected to the collision, both already incurred and reasonably expected
- Lost earnings: If your injuries prevent you from working, you may have a claim for income lost during your recovery.
- Reduced earning capacity: Permanent injuries may affect your ability to perform your current job or earn the same income in the future.
- Pain and suffering: Compensation may account for the physical pain and emotional distress linked with the injuries.
- Permanent impairment or disfigurement: Lasting limitations, scarring, or other permanent changes may affect the value of a claim.
- Other accident-related losses: Depending on the circumstances, additional losses may be recoverable under Missouri law and the applicable insurance policy.
When evaluating the worth of a claim, it is important to note that a serious injury can create losses that continue long after the initial hospital visit.
Policy limits are the ceiling, and they are separate from what a claim is worth. A person who suffers $200,000 in damages does not necessarily have a $200,000 UM claim. If the applicable UM policy provides a lower limit, that limit may restrict the amount available under that coverage, though additional coverage may exist and needs to be identified before the claim can be fully evaluated.
Do not assume the first settlement figure from your insurer represents the full value of your claim.
FAQs: St. Louis Uninsured Motorist Accident Lawyers
Will filing a UM claim raise my insurance rates?
A UM claim is made against your own policy, which is why people ask. How an insurer may treat a not-at-fault claim in its rating is governed by your policy and by Missouri insurance regulation rather than by a single rule that applies to everyone. If your insurer responds to a legitimate UM claim in a way that concerns you, that is worth discussing with an attorney.
Can I make a UM claim if I was a passenger?
You can make a UM claim as an injured passenger, depending on the vehicle you were riding in, the applicable policies, and the circumstances of the collision. Your own automobile insurance or another applicable policy may provide UM protection even when you were not driving at the time of the crash.
What if the uninsured driver who hit me fled the scene and I don't know who they are?
Missouri law expressly permits uninsured motorist coverage to apply when the identity of the owner or operator cannot be established because the driver left the scene, and Section 379.203 applies it whether or not the vehicles made physical contact. You can still pursue a claim under your own UM policy without identifying the at-fault driver, provided you can establish that another vehicle caused the crash.
What's the difference between uninsured motorist coverage and underinsured motorist coverage?
UM coverage applies if the at-fault driver has no insurance, while underinsured motorist coverage applies if the at-fault driver's policy limits are too low to pay for your damages. Missouri requires UM coverage on every policy issued in the state. Underinsured coverage is not required in the same way, so whether you carry it depends on your policy.
How long do I have to file a UM claim in Missouri?
Missouri generally gives you five years from the date of the collision to commence legal action, under Section 516.120. If the crash resulted in wrongful death, the deadline is three years under Section 537.100. Your insurer may also require notice much sooner than either deadline, so do not wait to get started.
Talk to Our St. Louis Uninsured Motorist Accident Lawyers

An uninsured driver should not be the reason a serious injury goes without an insurance claim being properly investigated. Your own policy may provide important protection, but the insurer's coverage position, the accident evidence, and the extent of your injuries all need to be examined.
Sumner Law Group, LLC is a St. Louis personal injury firm built around serious litigation. We prepare cases understanding that an insurance company may ultimately have to defend its position in court. Contact us today at (314) 669-0048 to request a free case review.